Private banking judgment does not travel well
Private banks have put AI to work on research, drafting and servicing. Suitability, cross-border rules and source-of-wealth judgment still live with relationship managers, and the 2026 evidence from benchmarks, supervisors and retirement data says that knowledge must be encoded before it leaves.
Download the PDFA private bank sells two things: access to the world's markets, and a person who knows the client. The first has been commoditized for a decade. The second is now the subject of the industry's largest technology investment, and in 2026 the evidence says the investment is landing on the wrong half of the business. The models are very good at research, drafting and servicing. They are not yet good at the question a relationship manager answers every day: is this right for this client, booked here, given where the money came from and what the family decided last time.
The numbers describe the stakes. Global financial wealth grew 10.7 percent in 2025 to $333 trillion, and cross-border wealth grew 8.4 percent to $15.7 trillion, with the ten largest booking centers taking almost 90 percent of new offshore flows; Hong Kong overtook Switzerland as the largest hub for the first time, and the UAE's cross-border book grew 11.1 percent.1 The number of high-net-worth individuals rose by nearly two million to 25.3 million, with a record $98.3 trillion in wealth, yet only 17 percent of them describe their advisory experience as seamless and personalized, 42 percent have had to restate their goals and preferences to the same firm more than once, and 60 percent of wealth executives admit their firm has no unified view of the client. The share of clients who keep a single firm has fallen from 39 percent in 2019 to 19 percent in 2025, and about $1.5 trillion moved to competitors of traditional firms between 2022 and 2025 (Exhibit 1).2
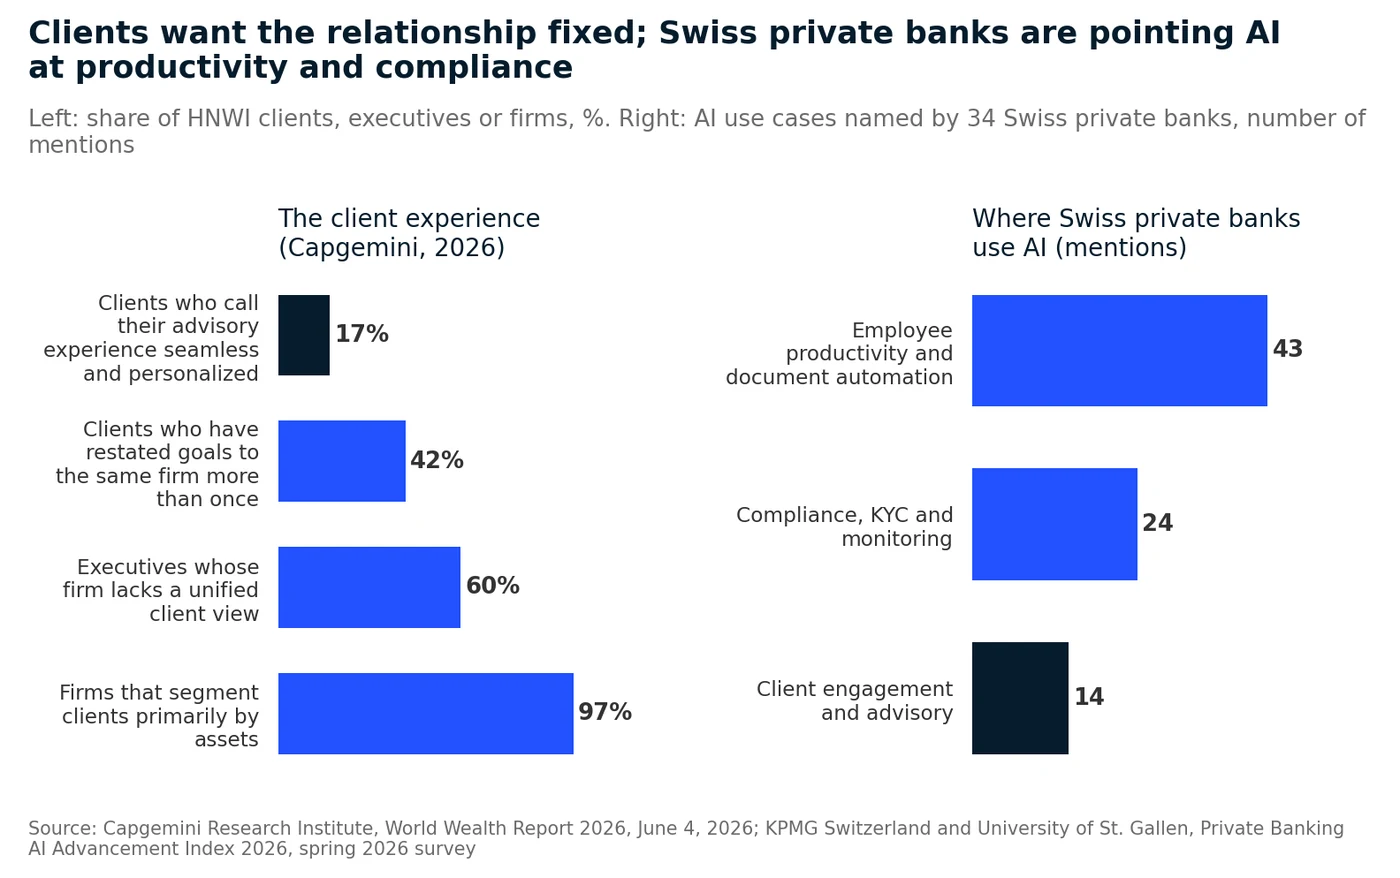
Against that, the industry's AI programs are real but narrow. Among 34 Swiss private banks surveyed in the spring of 2026 for the KPMG and University of St. Gallen AI index, 79.5 percent use AI in at least one operational setting, but client engagement and advisory drew only 14 mentions against 43 for employee productivity and document automation and 24 for compliance and monitoring; 94 percent reported zero AI-attributable revenue in 2025, and 76.5 percent describe their maturity as developing or ad hoc.3 In the UK, the FCA's August survey of 400 wealth management firms found 13 percent using AI tools, rising to 45 percent when firms considering it within twelve months are included.4 This paper argues that the gap between those two sets of numbers is not a deployment lag. It is a knowledge problem, and it has a demographic deadline.
The judgment that makes private banking private
Three kinds of knowledge separate a private bank from a brokerage, and none of them lives in a database. The first is suitability: whether a product fits this client's objectives, knowledge, capacity for loss and the regime that governs the account. The second is the cross-border rule book: which products may be offered to a client resident in one country, booked in a second and advised from a third. The third is source of wealth: the evidence and judgment that explain why a family's money is what it says it is. Each is applied by a relationship manager who learned the house convention from a predecessor, a compliance officer who remembers the last exception, and a committee minute nobody has indexed.
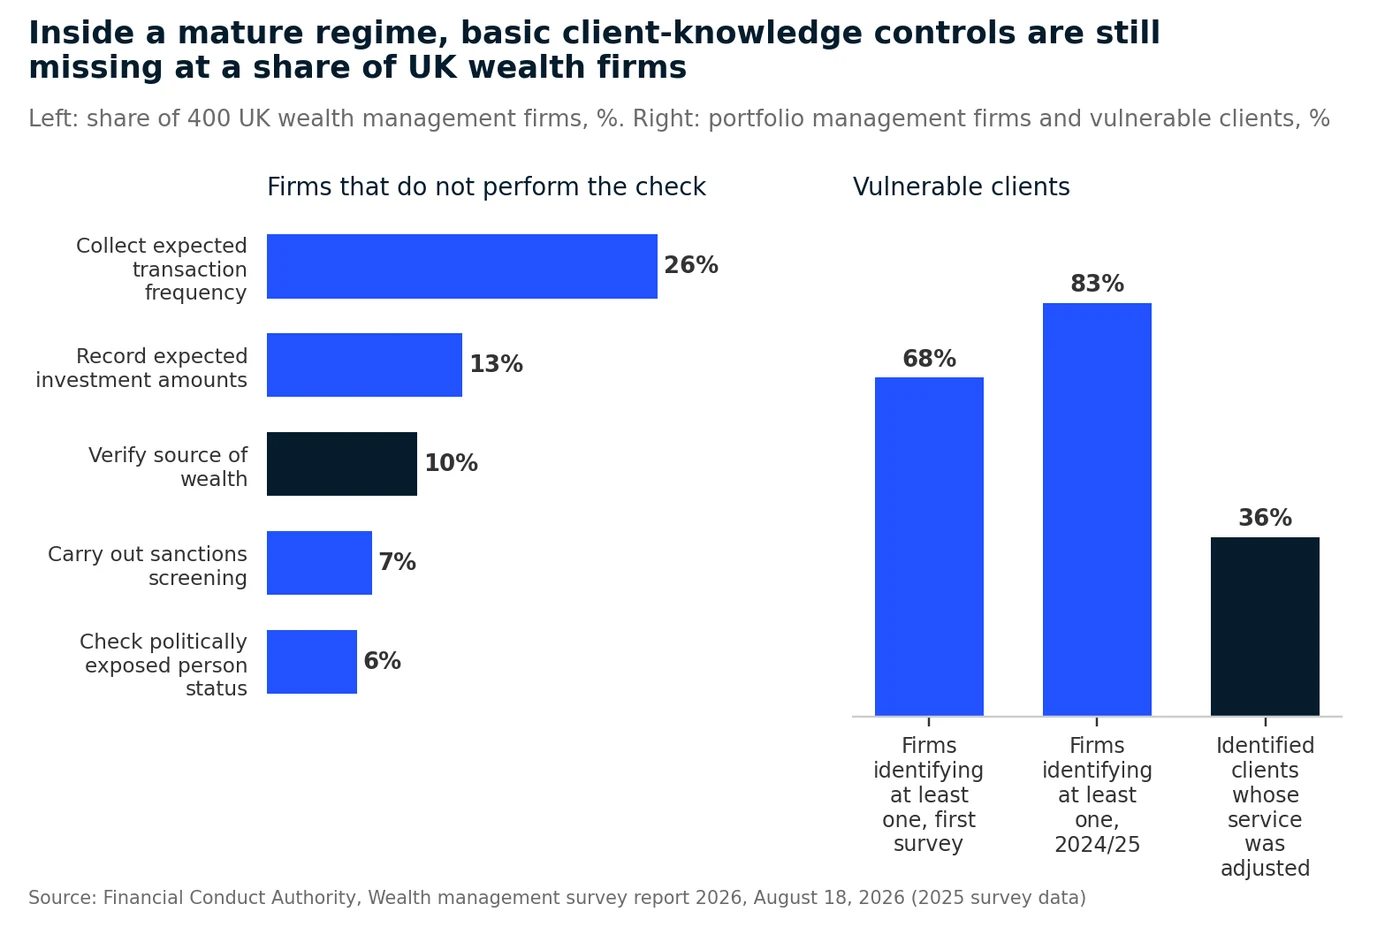
The UK survey shows how uneven that knowledge is even inside a mature regime. Around 10 percent of wealth firms do not verify source of wealth, around 6 percent do not check whether clients are politically exposed persons, around 7 percent do not carry out sanctions screening, 26 percent do not collect expected transaction frequency and 13 percent do not record expected investment amounts. On the conduct side, 83 percent of portfolio management firms identified at least one vulnerable client in 2024/25, up from 68 percent in the first survey, yet only around 36 percent of those clients had their service adjusted, and the regulator found that "some firms do not have policies, processes or training that are tailored to their services" (Exhibit 2).4 These are not technology failures. They are failures to turn what senior people know into something the rest of the firm, and its systems, can apply.
Switzerland shows the same pattern from the supervisor's side. At its April media conference, FINMA reported placing a growing number of asset management firms under intensive supervision in 2025, often for deficiencies "relating to compliance with conduct rules on suitability," alongside 113 on-site inspections at banks and 15 enforcement proceedings launched after deep dives, and it found that "outsourced functions were not always being adequately captured, documented and monitored."5 The cross-border cost is visible in the economics. The KPMG study of 68 Swiss private banks found the median cost-income ratio rose to 78.2 percent from 75.6 percent, that 10 of the 18 banks above 90 percent were subsidiaries of foreign banks, and that "banks should exit if they cannot achieve a critical size" onshore abroad; Julius Baer sold its Brazilian business, with CHF 9 billion of assets, in 2025.6 A booking center is not just a balance sheet. It is a body of rules and precedent that someone has to carry.
Research and servicing are solved. Suitability is not.
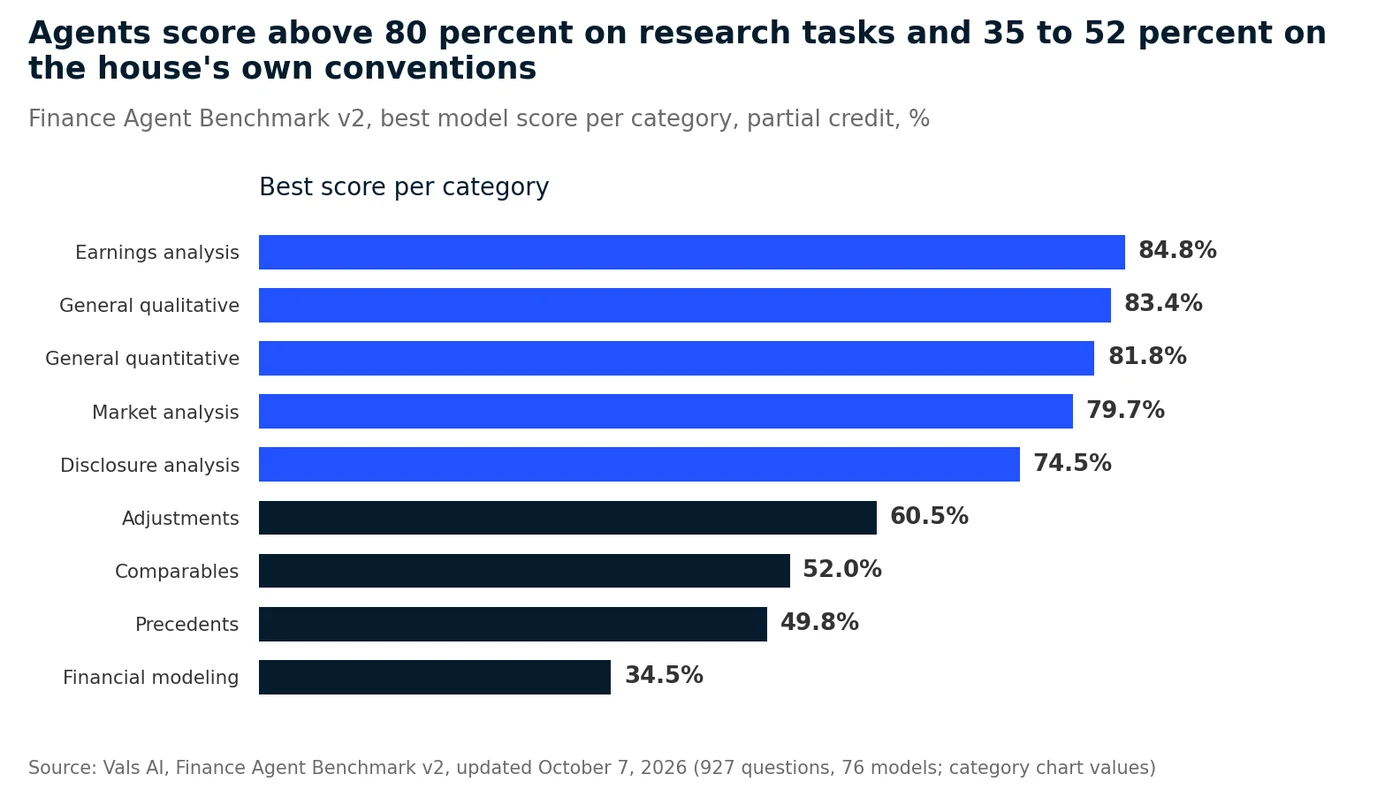
The 2026 benchmarks draw the line cleanly. On the Vals Finance Agent Benchmark v2, updated October 7 with 927 expert-reviewed questions and 76 models, the leading models score 84.8 percent on earnings analysis (Gemini 4 Argon), 83.4 percent on general qualitative work and 81.8 percent on general quantitative work. The scores fall to 60.5 percent on adjustments, 52.0 percent on comparables, 49.8 percent on precedents and 34.5 percent on financial modeling, and no model passes every part of a question more than 51 percent of the time (Exhibit 3).7 The tasks the models do well are the ones a research or servicing desk performs. The tasks they do badly depend on a house's conventions and prior decisions, which is what suitability and cross-border judgment are.
The reason is not model capacity. It is the absence of the institution's own definitions. In an April 2026 study, three frontier models were asked the same 100 analytical questions twice: once with only the database schema, and once with a four-kilobyte document of business definitions. Accuracy rose from between 45.5 and 50.5 percent to between 67.7 and 68.7 percent, the gains were significant at p below 0.01, and the three models were statistically indistinguishable in both conditions.8 A second 2026 study separated definitions from governance: a model writing database queries directly produced at least one hallucination in 79 percent of answers, schema retrieval cut that to 54 percent, business definitions to 40 percent while still leaking data across tenant boundaries in 35 percent of cases, and only definitions combined with access policy and validation before execution brought the rate to zero.9 In a private bank, the definitions are the suitability matrix, the booking-center rules and the source-of-wealth evidence standard. The access policy is which relationship manager may see which client, and the validation is what the bank has decided a person must approve.
The deployments confirm the split. UBS told investors in April that "nearly 90 percent of FA teams" use its flagship AI platform, which "delivers timely and personalized client insights"; it did not claim the platform decides what is suitable.10 The Swiss AI index classes only four of 73 private banks as leading and twelve as advanced against 27 that are aware and ten that are traditional, and notes that the advisory use case "remains less developed than internal productivity and compliance-related applications" given the "relationship-intensive, advice-driven nature" of the business.3 McKinsey's reading, published in April after a sell-off in listed wealth managers, is that fee rates on relationships above $1 million have held at about 104 basis points since 2019, that nearly 80 percent of affluent households still prefer a human relationship, and that the signal is "not a collapse in demand" but "a shift in value creation."11
Supervisors are asking for the same object in five jurisdictions
The regulators of the five main wealth centers spent 2026 moving in the same direction. In Switzerland, FINMA's annual report, published in April, records that about 50 percent of some 400 surveyed institutions had AI applications in use or under development, that around half have an explicit AI strategy, and that institutions see the largest AI risks in "data quality, data protection and the insufficient explainability of the results"; its position is "same business, same risks, same rules," applied through supervisory discussions, data surveys and targeted on-site inspections.12 In the UK, the FCA says of AI that "firms must use these tools responsibly and understand the risks" and that fair value "outcomes remain mixed"; its December consultation on client categorization would let individuals with at least £10 million of investable assets opt up to professional status, provided the recategorization "must be compatible with the Consumer Duty."4, 13
In Singapore, the Monetary Authority issued guidelines on AI risk management on October 7. Every financial institution must identify its AI use and maintain an inventory at an "appropriate level of granularity," assess the materiality of each use case, apply proportionate controls across data governance, testing, human oversight, monitoring and change management, and accept that it "remains accountable for AI used in the services" it delivers, including third-party models; Sections 3 and 4 apply from October 7, 2027, Sections 5 and 6 by October 7, 2028, and a consultation on agentic AI is planned for 2027.14 In the Gulf, the DFSA wrote to senior executive officers on June 4 setting out its "regulatory expectations on artificial intelligence risk management in the DIFC," covering governance and accountability, risk management, operational risk and third-party arrangements, with the reminder that "firms that rely on third parties remain responsible for compliance with DFSA requirements"; on July 30 it issued a 2026 AI survey to all authorized firms, due August 27.15, 16 The UAE central bank's February guidance note defines a "high-impact decision" as any AI-driven determination that materially affects a customer's access to financial products or services and expects fully autonomous AI to be limited to lower-risk processes.17 ADGM, reporting a 54 percent rise in assets under management in the first half, described its own AI approach as "designed to be governed, verifiable and human-accountable."18
In the United States, the SEC's examination priorities for fiscal 2026 name AI as a review area, covering automated investment tools, data sources and "AI washing," and put fiduciary duty to retail investors, the factors advisers document in recommendations, and recommendations to older investors at the center of adviser exams.19 Chair Paul Atkins told the FSOC's AI roundtable in March that "the Commission's mandate to protect investors is technology neutral," that "misconduct remains misconduct, regardless of the medium," and that an algorithm "does not weigh credibility or assess intent."20 Five regulators, one requirement: an inventory of what the AI does, a materiality judgment, a named human accountable for each decision, and the ability to explain which rule and which evidence were applied. None of those is a property of the model. All four are properties of the institution's knowledge, and today most of it is in the relationship manager's head.
The relationship manager's knowledge is leaving
Private banking has always stored its judgment in people, and in 2026 that storage is depreciating on both sides of the relationship. On the client side, the generational transfer has begun: UBS's first Global Next Generation Report, published in April, puts the wealth expected to change hands over the coming decades at $83 trillion, finds that 33 percent of next-generation respondents say their families are already transferring wealth and 25 percent are actively planning, and reports that 27 percent name peers as their most important source of succession advice against 21 percent for a wealth manager or private bank.21 The DIFC's February outlook cites an expected $124 trillion intergenerational transfer by 2048 and 9,800 new millionaires arriving in the UAE in 2025.22 The heir does not inherit the parent's relationship manager. The firm has to earn the relationship again, from a record of the family it may never have written down.
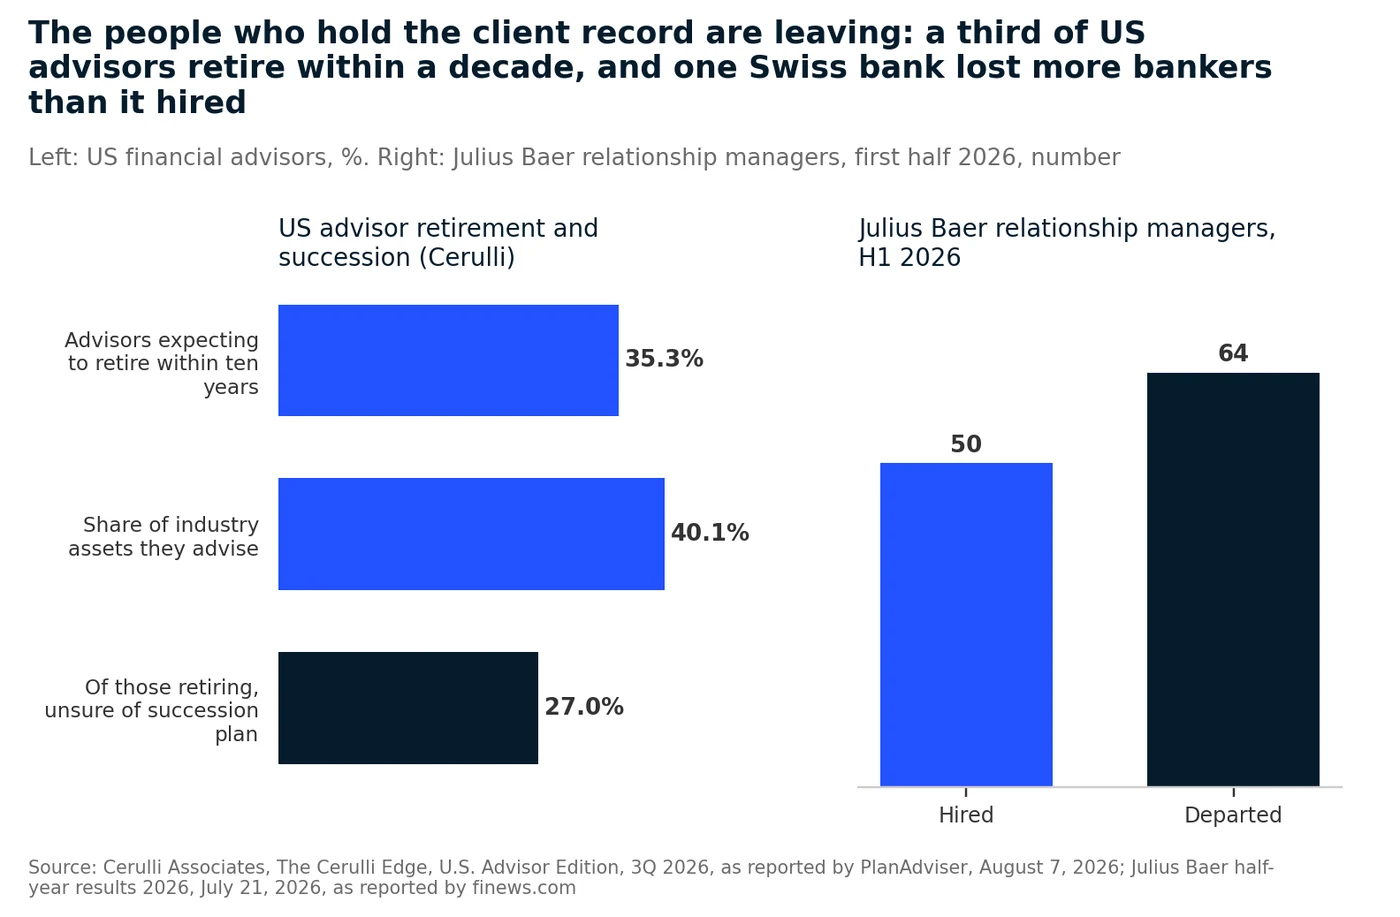
On the firm's side, the people who hold the record are closer to the exit than the industry likes to admit. Cerulli's third-quarter 2026 edition finds that 35.3 percent of US financial advisors expect to retire within ten years, that they oversee 40.1 percent of industry assets, nearly $14.5 trillion, and that 27 percent of them are unsure of their succession plan, which leaves roughly $4 trillion of client assets without a named successor; McKinsey projects a shortfall of 90,000 to 110,000 advisors by 2034 (Exhibit 4).11, 23 Julius Baer hired 50 relationship managers in the first half of 2026 and lost 64, ending with 1,247, and attributed a significant share of the departures to performance management; net new money ran at 2.2 percent annualized against a 4 to 5 percent target, and the bank expects its revised risk and compliance framework to keep weighing on inflows into 2027.24 UBS told analysts that "rotation among FAs remains elevated across the industry" and that earlier departures "will continue to show up in flows for a few quarters."10 Every departing relationship manager takes a working model of fifty families with them, and the firm keeps the CRM record.
The structural problem is that the firm's record is not the relationship manager's knowledge. Capgemini's 1,317 surveyed relationship managers spend 41 percent of their time on operational tasks, and 76 percent want AI to take routine work away; but 97 percent of firms still segment clients primarily by assets under management, which is why 42 percent of clients repeat their goals.2 The reason a structured product was declined for the second son but approved for the holding company, the booking-center constraint that made the Singapore account the right one: these are the facts the next relationship manager and the next model need, and the CRM does not hold them.
What the people shaping the next four years expect
The views worth weighting are those of people who run the capital, supervise it or measure it. In 2026 they were specific about the period to 2030.
- The gap between AI-first and traditional firms will open fast. BCG's 2026 wealth report estimates that AI-first wealth managers can gain 25 to 30 percent in capacity across key workflows and lift revenue per advisor by 15 to 20 percent, and its coauthor Michael Kahlich warned that "the gap between AI-first firms and traditional operating models could widen very quickly."1 Swiss private banks expect the money to arrive later than the capacity: 85 percent of the index respondents expect a measurable cost effect by 2028 and 70 percent expect cumulative savings of 3 percent or more, but 21 percent still expect zero revenue effect and another 21 percent call it too uncertain to predict.3 KPMG's Christian Hintermann expects the number of Swiss private banks to fall "well below 70 by 2030," from 79 at the end of May 2026.6
- The supervisory calendar is fixed. MAS's guidelines bind from October 2027 and in full by October 2028, with agentic AI guidance to be consulted on in 2027.14 The DFSA's 2026 AI survey closed on August 27, and the FCA plans a shorter 2027 wealth survey focused on portfolio management.4, 16
- Bought context will not stick. Gartner predicted in September that by 2028, 70 percent of enterprises will abandon agentic AI built for them by vendors' forward-deployed engineers, and that less than 20 percent of such engagements will turn recurring customer needs into product capability.25 In Swiss private banking, 24 of 34 surveyed banks source AI as off-the-shelf vendor solutions and only four build models in house.3
- The macro bet is large and unproven. The BIS General Manager, Pablo Hernández de Cos, told the Global Fintech Fest in September that industry participants expect global AI-related investment to rise from about $500 billion to between $3 trillion and $4 trillion by 2030 while the median productivity estimate is about half a percentage point a year, and that "should the returns to AI disappoint, a pullback in investment could turn today's capital expenditure boom into a bust."26
Our own expectation, grounded in those views, is that the period to 2030 will sort private banks by one variable: whether their suitability logic, booking-center rules and precedent exist in a governed, machine-usable form or only in people. Models will keep converging; the benchmarks already show three frontier systems indistinguishable once given the same definitions. Supervisors in Bern, London, Singapore, Dubai and Washington will keep moving from "do you use AI" to "which rule, whose authority, which evidence," and the advisors who hold the unwritten rules will keep retiring at the rate Cerulli measures. By 2028 we expect the first suitability findings in which a supervisor asks a bank to state the logic its AI applied and the bank answers from interviews. By 2030 we expect the gap BCG describes to show up in net new money before it shows up in cost, and the firms on the right side of it to be those that treated institutional judgment as an asset with an owner, a version and an audit trail.
Encoding the private bank's judgment: four moves
The banks that are moving ahead are not buying another advisor copilot. They are making their own judgment explicit, in roughly this order, and governing it as they would a model.
1. Start with the twenty decisions a relationship manager defends
Begin with the decisions most often challenged by a client, a compliance officer or a supervisor: a suitability determination for a complex product, a cross-border offering to a non-resident, a source-of-wealth acceptance, a vulnerability adjustment, a concentration exception. For each, write down the concepts it uses, the evidence it requires, the thresholds by booking center and client classification, and who may decide. That inventory is what MAS now requires and what the DFSA and FINMA are asking for.12, 14, 15
- Concrete marker: Each priority decision has a named owner, an explicit definition set and an evidence standard that a system can check before a recommendation reaches a client.
- Concrete marker: Suitability and cross-border rules carry jurisdiction, booking center, client classification and effective date, not a single global label.
2. Mine precedent from the files, not from the workshop
Relationship managers cannot fully write down how they decide, but their decisions are recorded: suitability reports, declined-product logs, exception approvals, source-of-wealth memos, family-office minutes. Use models to extract the conventions those records reveal, then have senior relationship managers and compliance officers confirm or correct them. The 2026 studies show the gain from a few kilobytes of confirmed definitions exceeds the gain from a model upgrade.8
- Concrete marker: Precedent is stored as a fact pattern, a decision and a reason, so a new case in a different booking center can be matched to it.
- Concrete marker: Relationship managers approaching retirement spend their final year validating extracted client and precedent knowledge, and the firm measures how much of each book has been captured.
3. Attach authority and access to meaning
A suitability rule without a decision right is a glossary. Each rule, definition and precedent should carry who may apply it, who may change it, who must approve a departure, and which outputs require a human before a client sees them. This is the step the 2026 evidence weights most: definitions alone still leaked data in 35 percent of cases; definitions with policy and validation did not.9 In a private bank, access is itself a conduct rule: which relationship manager may see which client is a matter of banking secrecy in every booking center.
- Concrete marker: Every AI-assisted recommendation records the suitability rule, the booking-center constraint, the evidence and the approver applied, so a reviewer or supervisor can trace it without an interview.
- Concrete marker: The cases that must go to a human, such as a vulnerable client, a politically exposed person or a cross-border product restriction, are specified in advance and the system enforces them.
4. Govern the knowledge like a model, and the vendor like an outsourcer
Private banks already run model risk management and outsourcing oversight, and FINMA's finding that outsourced functions "were not always being adequately captured, documented and monitored" is a warning for AI sourcing in particular.5 Apply the same discipline to the knowledge layer: an inventory with owners, review cycles, change control and independent validation. The bank's judgment then survives staff turnover, model replacement and the vendor cycle Gartner expects to end badly for most buyers.25
- Concrete marker: The suitability, cross-border and source-of-wealth knowledge base has an inventory, named owners, a review cycle and a change log, like any material model.
- Concrete marker: Replacing the language model or the vendor platform does not require rebuilding the bank's definitions, precedent or decision rights.
The leadership test
No private bank has finished this work. Leaders can locate their institution with six questions:
- If a supervisor asked which suitability rule and which precedent an AI-assisted recommendation applied, would we answer from the system or from the relationship manager?
- For each booking center, is the cross-border rule set written in a form a system can apply, or does it live with the people who have been in that center longest?
- When a senior relationship manager leaves with fifty families, what fraction of what they knew about those families is anywhere other than in their head?
- Do we know which client decisions we have decided a human must make, and does every AI tool we have deployed know it too?
- Is our source-of-wealth judgment an evidence standard with an owner, or a set of habits that differ by desk?
- If we replaced our AI vendor next year, which of our rules, precedents and decision rights would we have to rebuild?
Firms that can answer these questions from the system have encoded their judgment, whatever they call it. Those that cannot are scaling the half of the business the models already do well, while the half that makes them a private bank stays unstructured and walks out with 35 percent of advisors a decade.
Private banking judgment does not travel well because it was never written to travel. It was written, when it was written at all, for one desk, one booking center and one generation of clients. The next generation of clients, the next generation of relationship managers and the next round of supervisory questions arrive together before 2030. The firms that scale advice across borders and survive their audits will be the ones that make the relationship manager's judgment the institution's judgment: governed, versioned and usable by whatever model they deploy next.
Get the PDF
A formatted copy of “Private banking judgment does not travel well” with every exhibit and source, for reading offline or sharing with your team. We will email you a copy too. You will only be asked once.
Bring one number your institution argues about. In 30 minutes the Penomic Research team maps how each team defines it, who owns each version and where AI would get it wrong. You keep the write-up.
Book a Diagnostic Or request a private architecture briefingNotes
- Boston Consulting Group, Global Wealth Report 2026: The Great Reordering, press release "Hong Kong surpasses Switzerland as the largest cross-border wealth hub," May 27, 2026, including the quoted remarks of coauthor Michael Kahlich and BCG's estimates for AI-first wealth managers. bcg.com (press release)
- Capgemini Research Institute, World Wealth Report 2026 (30th edition), June 4, 2026 (survey of 1,317 relationship managers across 24 markets, plus HNWI and executive surveys), as reported by IFA Magazine. ifamagazine.com (June 4, 2026)
- KPMG Switzerland and University of St. Gallen, Private Banking AI Advancement Index 2026, spring 2026 survey (34 responding banks; index of 73 banks), published alongside the Clarity on Swiss Private Banks study, June 2026. assets.kpmg.com (index PDF)
- Financial Conduct Authority, Wealth management survey report 2026, August 18, 2026 (400 firms in the wealth management portfolio; 2025 survey data). fca.org.uk/data/wealth-management-survey-report-2026
- FINMA, annual media conference press release, April 21, 2026 (2025 supervisory activity: 113 on-site inspections at banks, 15 enforcement proceedings launched after bank deep dives, asset managers placed under intensive supervision over suitability conduct rules). finma.ch (press release)
- KPMG Switzerland and University of St. Gallen, Clarity on Swiss Private Banks 2026, June 24, 2026 (68 banks, about 85 percent of the population), and accompanying press release quoting Christian Hintermann on the number of banks by 2030. kpmg.com (press release); assets.kpmg.com (study PDF)
- Vals AI, Finance Agent Benchmark v2 leaderboard, updated October 7, 2026 (927 expert-reviewed questions, nine categories, 76 models; partial-credit scoring; category chart values). The page's prose gives lower figures for adjustments (56.29 percent) and precedents (36.37 percent); the chart values are used here. vals.ai/benchmarks/fabv2
- M. Rumiantsau and I. Fokeev, Semantic Layers for Reliable LLM-Powered Data Analytics: A Paired Benchmark of Accuracy and Hallucination Across Three Frontier Models, arXiv:2604.25149, April 28, 2026 (100 questions; Claude Opus 4.7, Claude Sonnet 4.6, GPT-5.4; 4 KB semantic layer). The authors work for Cube, a semantic-layer vendor. arxiv.org/abs/2604.25149
- A. Sasidharan Pillai, GROUND: Reducing Hallucinations in LLM-Based Enterprise Analytics Through Governed Semantic Definitions, arXiv:2608.26157, July 2026, Section 8.1 (100 questions; any-hallucination rates 79, 54, 40 and 0 percent; semantic-only condition leaks data across tenant boundaries on 35 percent of questions). arxiv.org/html/2608.26157
- UBS Group AG, first quarter 2026 results, analyst call transcript of April 29, 2026 (Form 6-K filed April 30, 2026): remarks of Sergio Ermotti on the AI platform and of Todd Tuckner on advisor rotation and flows. sec.gov (transcript)
- McKinsey, The signal in the sell-off: Wealth management's value in the AI era, April 8, 2026 (fee-rate and client-preference figures cite McKinsey's earlier research; 90,000 to 110,000 advisor shortfall projected by 2034). mckinsey.com (article)
- FINMA, Annual Report 2025, chapter "FINMA's digital strategy, data-driven supervision and digitalisation in the financial sector," published April 2026 (survey of around 400 supervised institutions conducted in early 2025). report.finma.ch/2025 (annual report)
- Financial Conduct Authority, CP25/36, Client categorisation, December 8, 2025 (comments closed February 2, 2026), as summarized by Simmons & Simmons. Late-2025 source used because the 2026 policy statement had not been published at the time of writing. simmons-simmons.com (briefing)
- Monetary Authority of Singapore, Guidelines on Artificial Intelligence Risk Management, media release, October 7, 2026 (Sections 3 and 4 effective October 7, 2027; Sections 5 and 6 by October 7, 2028; agentic AI consultation planned for 2027), as republished by The Asian Banker. theasianbanker.com (MAS release); mas.gov.sg (original)
- Dubai Financial Services Authority, Dear SEO letter, "DFSA regulatory expectations on artificial intelligence risk management in the DIFC," June 4, 2026. dfsa.ae (SEO letters)
- Dubai Financial Services Authority, Dear SEO letter "2026 Artificial Intelligence Survey," July 30, 2026 (responses due August 27, 2026), as reported in Waystone Compliance Solutions, Regulatory Update July 2026, ME Region. compliance.waystone.com (July 2026 update)
- Central Bank of the UAE, Guidance Note on the responsible use of artificial intelligence and machine learning in the financial sector, February 23, 2026, press release as republished by The Asian Banker; "high-impact decision" definition and autonomy limits as summarized by Hadef & Partners, "AI in banking and finance in the UAE 2026." theasianbanker.com (CBUAE release); hadefpartners.com (briefing)
- Abu Dhabi Global Market, "ADGM reinforces Abu Dhabi's standing as a global financial hub with 54 percent growth in AUM and almost 14,000 active licences," press release, September 8, 2026 (first half 2026 versus first half 2025). zawya.com (press release)
- US Securities and Exchange Commission, Division of Examinations, Fiscal Year 2026 Examination Priorities, November 17, 2025, as summarized by Akin. Late-2025 source: the priorities govern the fiscal year ending September 30, 2026 and have no 2026 replacement. akingump.com (alert)
- Paul S. Atkins, remarks at the Financial Stability Oversight Council Artificial Intelligence Innovation Series Roundtable on Strategy and Governance Principles, March 4, 2026, as republished by the CLS Blue Sky Blog, March 5, 2026. clsbluesky.law.columbia.edu (remarks)
- UBS, Global Next Generation Report 2026, April 28, 2026, as reported by WealthBriefing. wealthbriefing.com (April 2026)
- Dubai International Financial Centre, Global Wealth Outlook: Rethinking growth in a changing world, Dubai Media Office release, February 24, 2026 (9,800 figure attributed to a Henley & Partners estimate). mediaoffice.ae (release)
- Cerulli Associates, The Cerulli Edge, U.S. Advisor Edition, 3Q 2026, as reported by PlanAdviser, "Adviser recruitment, development gain importance as retirements rise," August 7, 2026. planadviser.com (August 7, 2026)
- Julius Baer Group, half-year results 2026, July 21, 2026, as reported by finews.com, "Julius Baer posts record profit, but one key challenge remains." finews.com (July 21, 2026); juliusbaer.com (results)
- Gartner, "Gartner predicts 70 percent of enterprises will abandon agentic AI built by vendor forward-deployed engineering by 2028," press release, September 29, 2026. gartner.com (press release)
- Pablo Hernández de Cos, "Artificial intelligence, growth and financial stability: challenges for central banks," speech at the Global Fintech Fest, Mumbai, September 10, 2026. bis.org (speech)
Copyright © 2026 Penomic. All rights reserved. Exhibits are drawn by Penomic Research from the data published in the sources cited; no third-party figures are reproduced. Benchmark results are reported as published and reflect model versions available at the dates shown.
More from Penomic Research
The institutional intelligence gap
Financial institutions have wired AI into their data. Value stalls because the firm's definitions, policy, precedent and judgment were never made machine-usable.
Why AI pilots stall after the demo
2026 surveys, bank disclosures and agent benchmarks show that AI pilots stall because the institution's definitions, precedent and decision rights were never written down and governed.
Govern the agent through the institution's decision rights
2026 adoption data, agent benchmarks, misalignment studies and supervisory statements show why agent control belongs in the institution's decision rights, not the model's prompt.